S$1.50B Land Bid · $1,179 psf ppr · ~835 Homes Above Hougang MRT & a 300,000 sq ft Mall
Tracking every milestone on the Hougang Central GLS site — from tender award to site plan to launch. Last updated: .
The S$1,500,738,338 award sets the highest land rate ever paid for an Outside Central Region mixed-use GLS site, with CICT taking 100% of the commercial component.
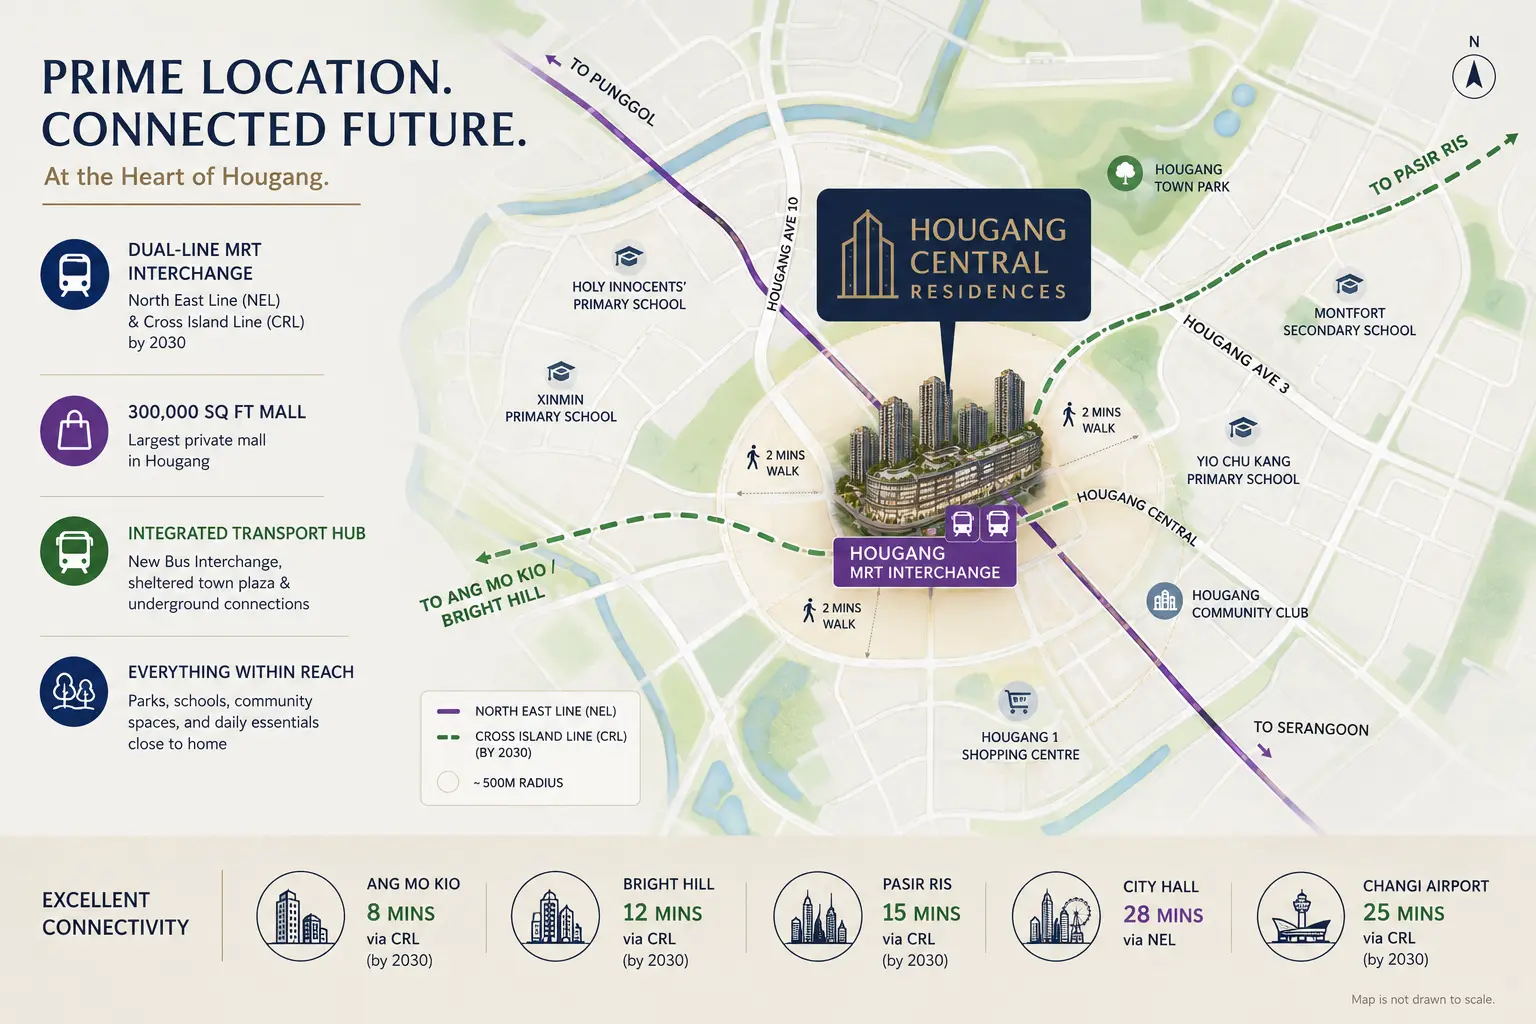
See the full award detail →Cross Island Line Phase 1 is LTA-committed and timelined for 2030, turning NE14 into an NEL/CRL interchange — directly beneath the development.
Explore the connectivity →More than seven years without new private supply in Hougang, against a District 19 resale market up 47.7% between 2020 and Jan–Nov 2025.
See what this means for pricing →The Hougang Avenue 10 / Hougang Central GLS site was awarded on 14 January 2026 to a consortium of CapitaLand Development, UOL Group, Singapore Land Group and Kheng Leong, with CapitaLand Integrated Commercial Trust taking 100% of the commercial component. The price was S$1,500,738,338, or $1,179 psf per plot ratio — the highest land rate recorded for an Outside Central Region mixed-use GLS site.
Record for an OCR mixed-use GLS site
| Site | Land Rate | Awarded | Transport Obligation |
|---|---|---|---|
| Hougang Central (this site) | $1,179 psf ppr | Jan 2026 | Integrated Transport Hub + ~300,000 sq ft mall |
| Chencharu Close, Yishun | $980 psf ppr | Sep 2025 | Bus interchange + hawker centre |
| Tampines Street 94 (Pinery Residences) | $1,004 psf ppr | Sep/Oct 2024 | None |
| Tampines Avenue 11 (Parktown Residence) | $885 psf ppr | Jul 2023 | Bus interchange + hawker centre |
Source: URA / HDB tender records; EdgeProp and CBRE commentary, September 2025 and January 2026. Hougang Central carries the heaviest integration obligations on this ladder — a full transport hub plus a mall — which is part of why its land rate sits above the others.
From land release to estimated completion — every confirmed milestone and every estimate, clearly separated.
HDB's Additional Conditions of Tender set the site at 46,898 sqm, gross plot ratio 2.5, permissible gross floor area 105,521–117,245 sqm, with at least 70,805 sqm residential, at least 6,500 sqm of bus interchange, and up to 39,940 sqm of other commercial floor area.
CapitaLand Development, UOL Group, Singapore Land Group and Kheng Leong take the residential component; CapitaLand Integrated Commercial Trust takes 100% of the commercial component. It is the highest land rate recorded for an OCR mixed-use GLS site.
Stack orientation, facing and the confirmed unit mix are only knowable once the developer publishes the site plan. Register below to receive it the day it lands.
An internal planning estimate, not a developer announcement. Some secondary market commentary has floated an earlier showflat date; that remains unconfirmed.
Hougang MRT gains a second line, adding direct north-east and eastern journeys to Ang Mo Kio, Pasir Ris and beyond, mid-way through the development's construction.
Longer than a standalone condominium because the build includes the Integrated Transport Hub, the rebuilt bus interchange and the mall. No completion deadline has been publicly disclosed at this edition.
Estimated dates are analyst and planning projections based on tender conditions and typical development cycles — they are not developer-confirmed.
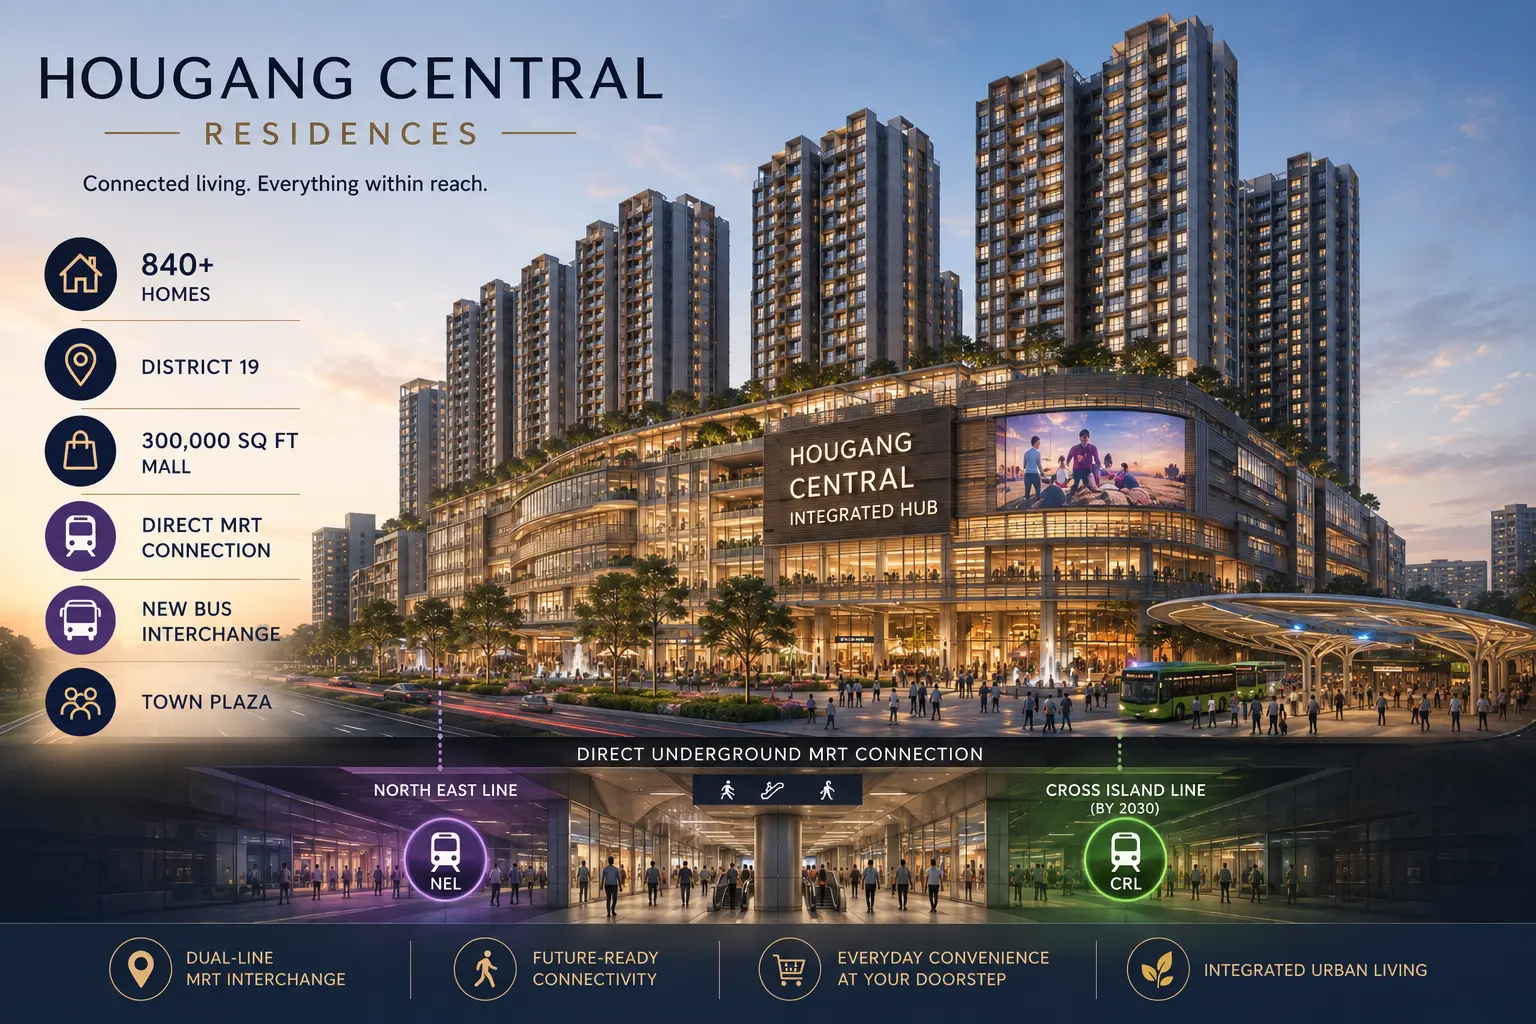
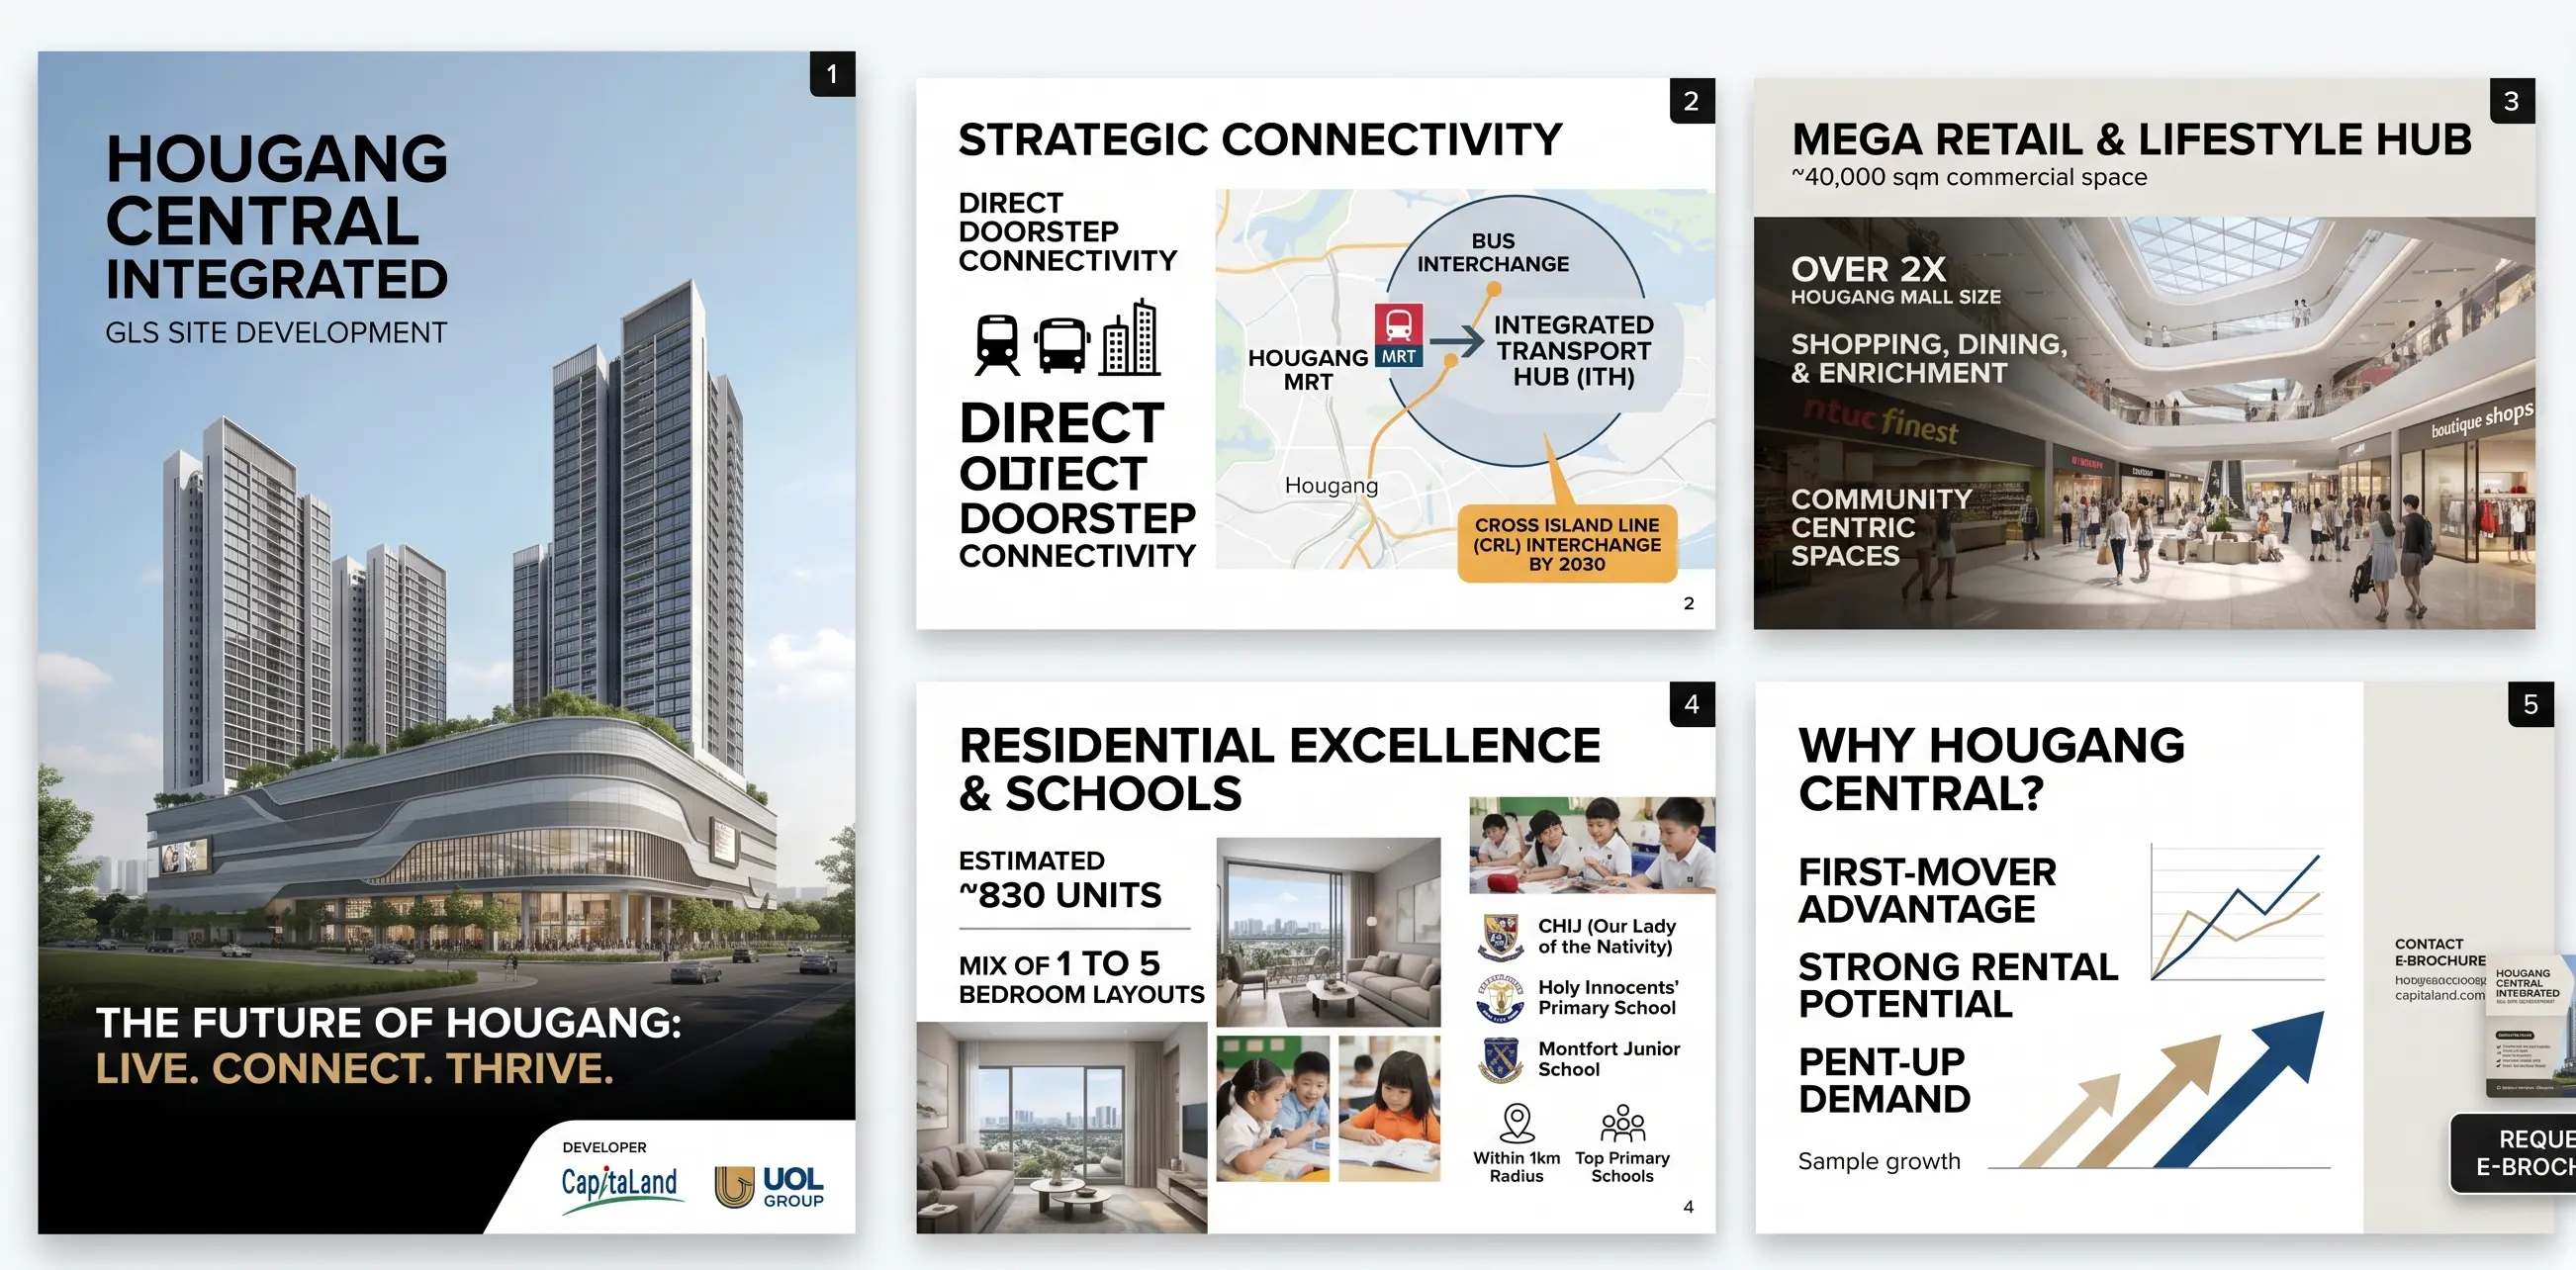
Hougang Central Residences is a 99-year leasehold integrated development on the Hougang Avenue 10 / Hougang Central GLS site in District 19 — approximately 835 homes built above a new Integrated Transport Hub that puts Hougang MRT (NE14) and a rebuilt bus interchange under one roof, together with a CICT-owned mall of about 300,000 sq ft. It is Hougang's first new private residential site released in over a decade, awarded on 14 January 2026 for S$1,500,738,338 ($1,179 psf ppr).
Last updated:
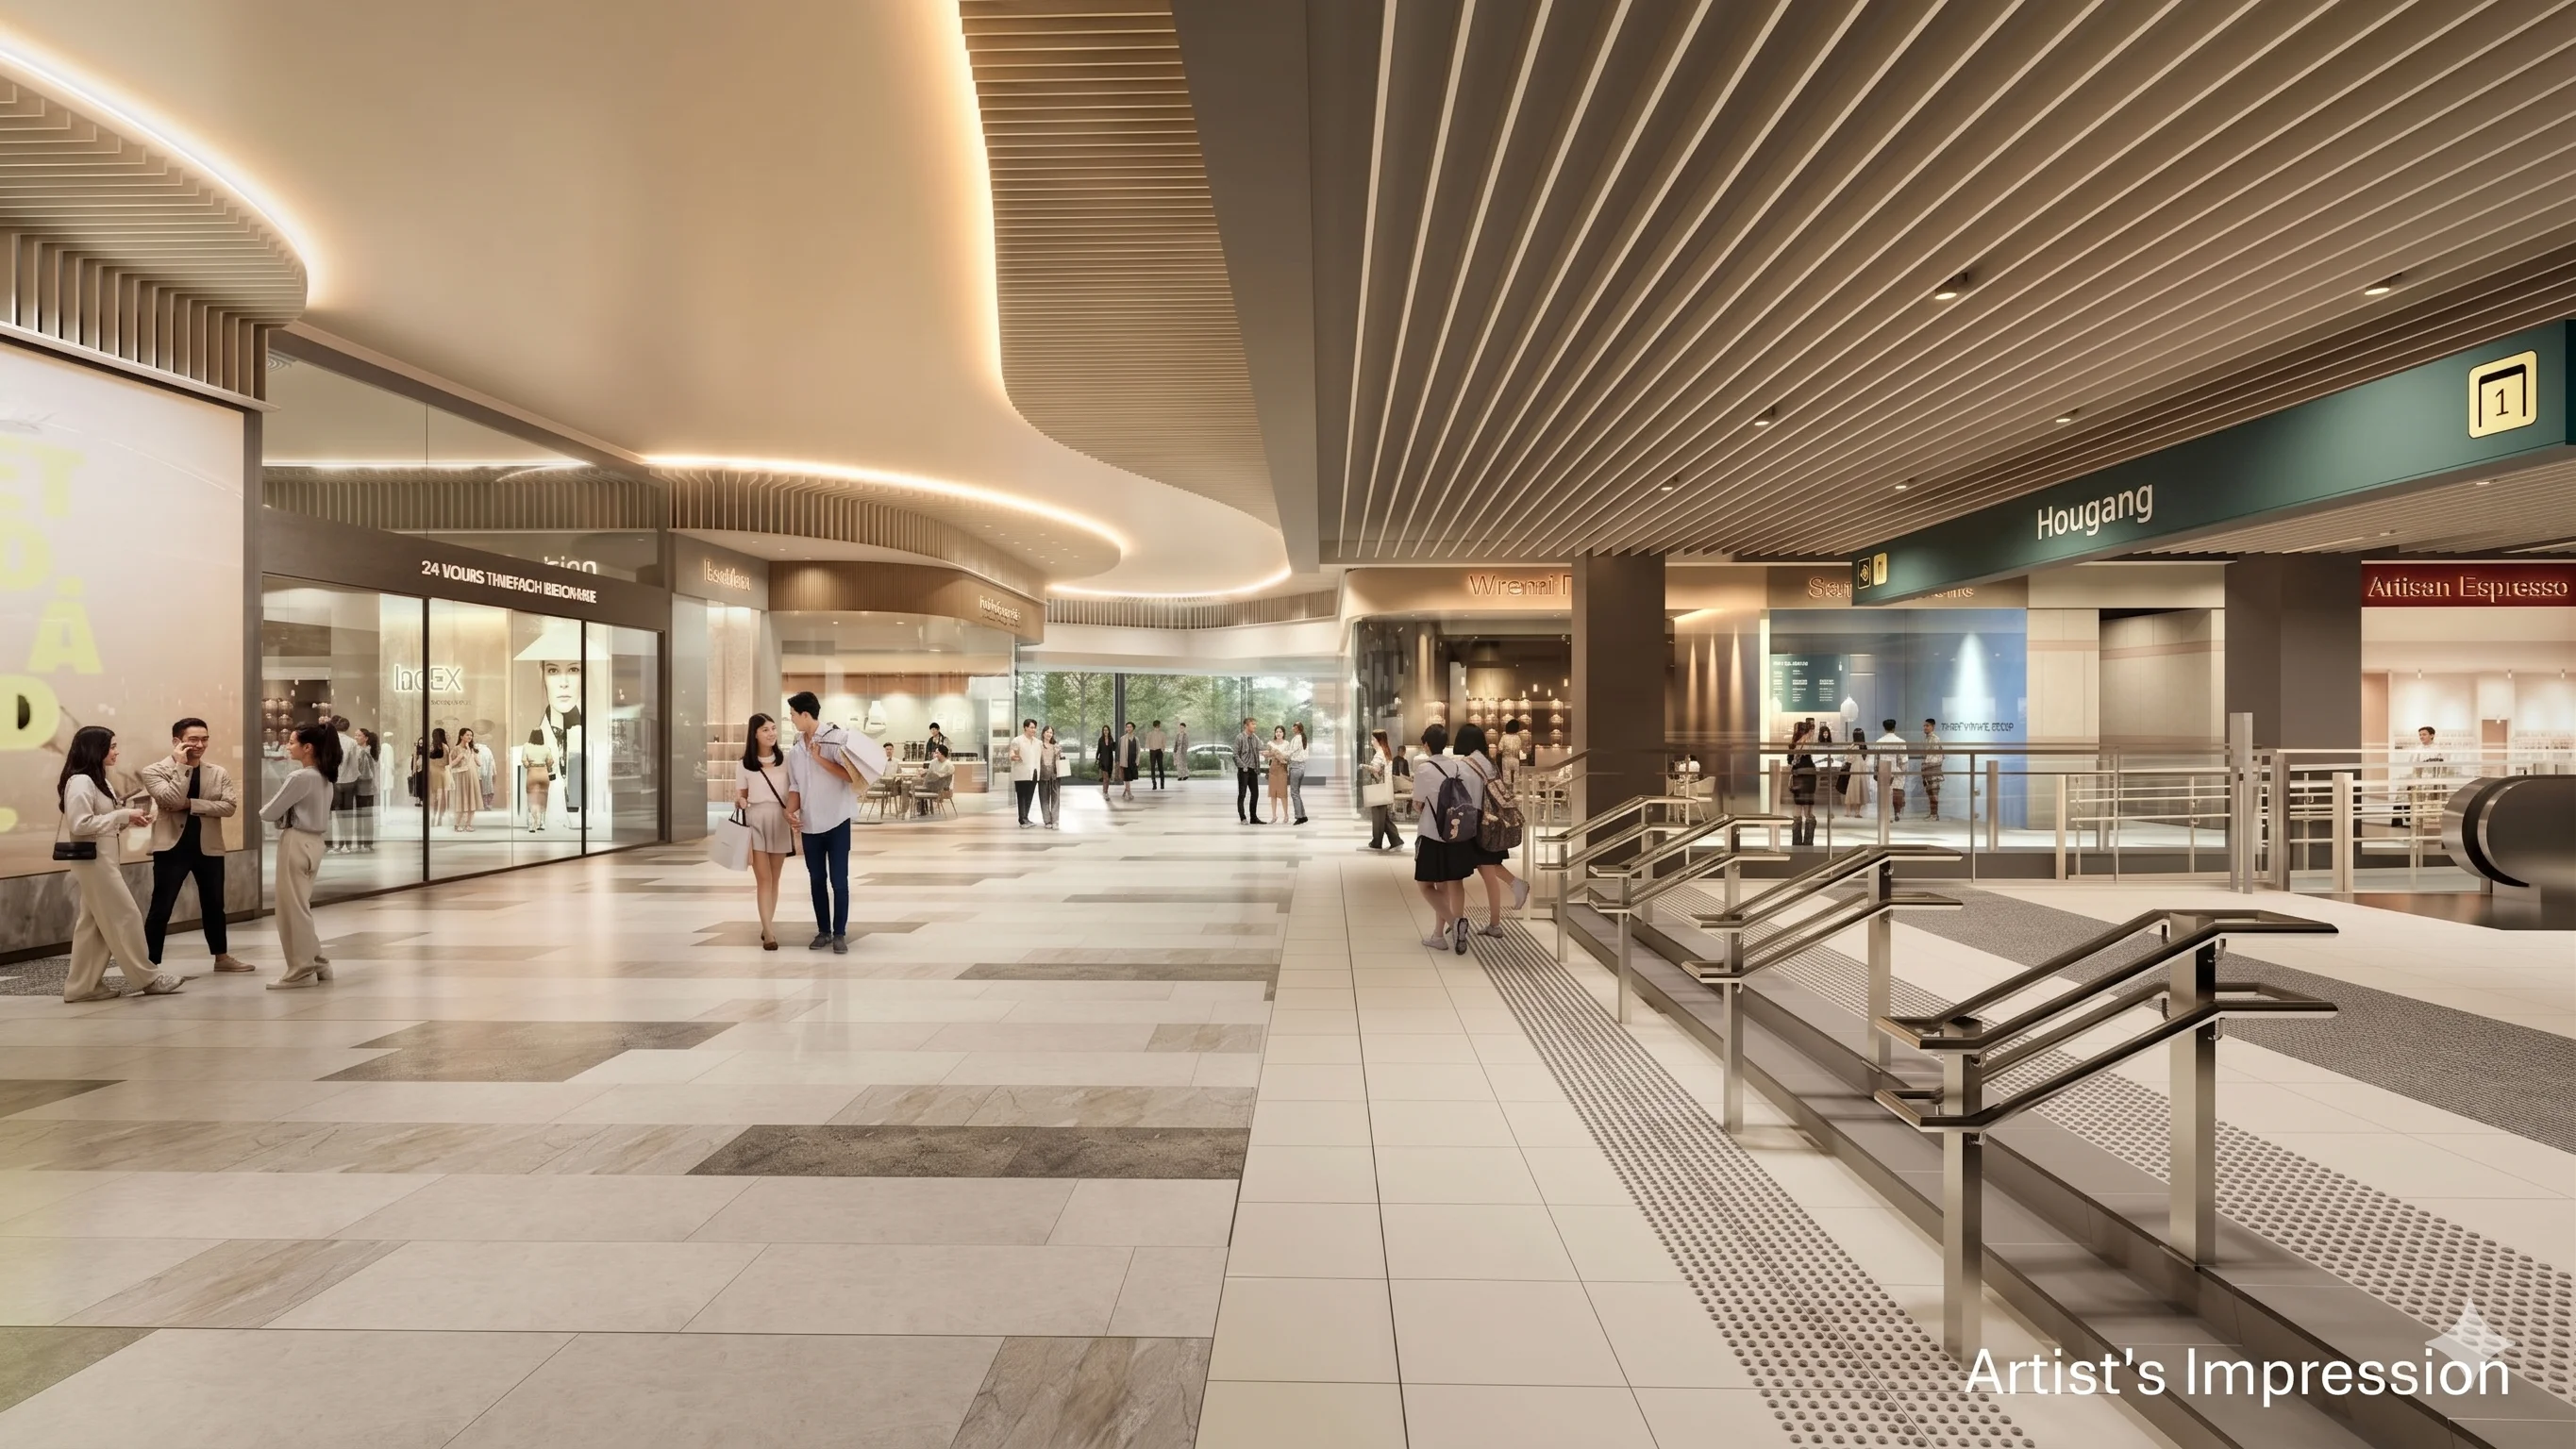
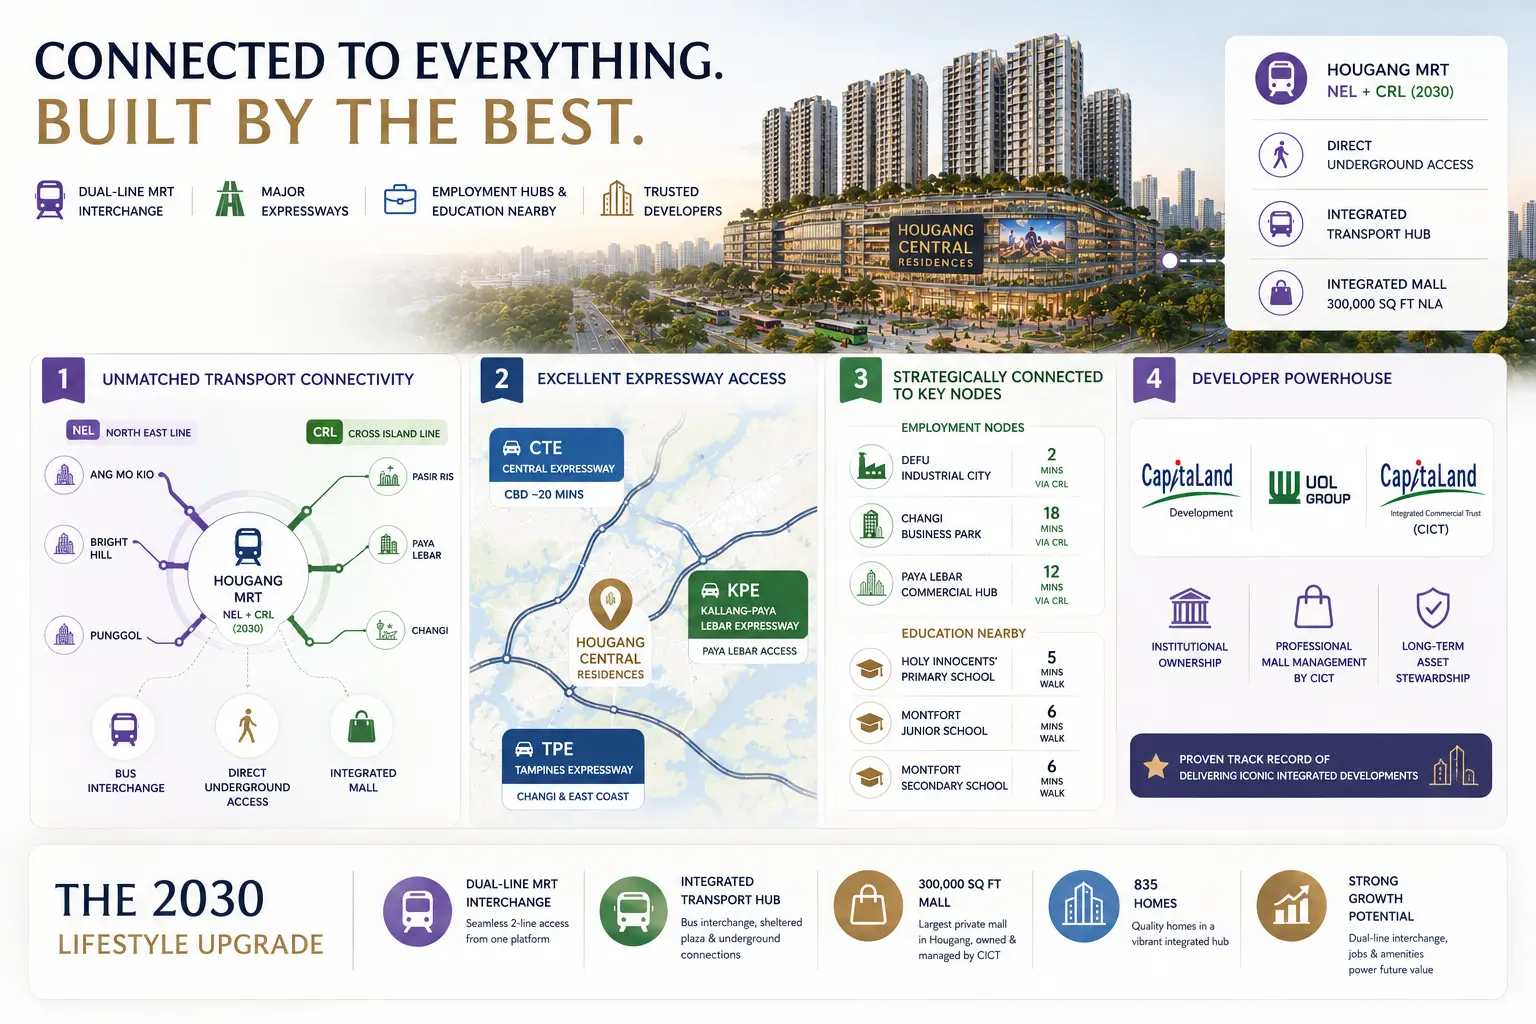
The development is built on the existing Hougang Bus Interchange footprint and integrates directly with Hougang MRT (NE14). This is in-building access, not a walk to the station — a package no other Hougang address has ever offered.
Hougang MRT becomes an NEL and Cross Island Line interchange when CRL Phase 1 opens, targeted by 2030 under LTA's committed programme — a second axis arriving mid-construction, before residents collect keys.
Up to 39,940 sqm of commercial floor area is permitted — around 300,000 sq ft of net lettable retail, owned outright by CapitaLand Integrated Commercial Trust, which runs it as a long-term income asset rather than selling and moving on.
Montfort Junior School, CHIJ Our Lady of the Nativity, Holy Innocents' Primary School, Xinmin Primary School and Rosyth School are among those in the surrounding area. Distances are unverified against MOE SchoolFinder — check the official tool before assuming any Phase 2C(S) priority.
The Kallang–Paya Lebar Expressway and Central Expressway both connect directly from the Hougang Central precinct, with Tampines Road and Upper Paya Lebar Road as the arterial roads bounding the site.
Hougang has had no new private launch since The Florence Residences in 2019. District 19's median resale price rose from $1,112 psf in 2020 to $1,642 psf over January–November 2025 — up 47.7%, ahead of the OCR-wide 45.8%. (Source: URA data via ERA Research, 8 December 2025.)
Last updated:
Hougang Central Residences occupies the first private residential Government Land Sale site released in Hougang in over a decade — a 46,898 sqm parcel at Hougang Avenue 10 / Hougang Central, on the footprint of the town's existing bus interchange. It was awarded on 14 January 2026 for S$1,500,738,338, or $1,179 per square foot per plot ratio, to a consortium of CapitaLand Development, UOL Group, Singapore Land Group and Kheng Leong, with CapitaLand Integrated Commercial Trust taking the entire commercial component. (Source: HDB / URA tender records and the CapitaLand/CICT joint release, 14 January 2026.)
What the consortium is required to build is unusually specific. HDB's tender conditions mandate a minimum 6,500 sqm bus interchange within the development — including a 400 sqm commercial concourse — consolidated with Hougang MRT into a single Integrated Transport Hub. Up to 39,940 sqm of further commercial floor area is permitted, which CICT has described as roughly 300,000 sq ft of retail: on completion, the largest mall in Hougang.
The residential component sits above all of it. At a gross plot ratio of 2.5 and a permissible gross floor area of 105,521–117,245 sqm — of which at least 70,805 sqm must be residential — the tender projection is approximately 835 homes. Developer marketing material has since referred to 840-plus homes across a one- to five-bedroom mix. The final count and mix will be confirmed when the site plan is published, expected in late 2026 or early 2027.
For a District 19 buyer, the significance is scarcity on two axes at once. Hougang has had no new private launch since The Florence Residences in 2019, while roughly 31,000 HDB flats of three rooms and larger across Hougang, Punggol, Sengkang and Serangoon reached the end of their five-year Minimum Occupation Period between 2020 and 2026 (ERA Research). That is a large, local, upgrade-ready pool with nowhere new to go — until now.
Hougang Central Residences — the development on the Hougang Avenue 10 / Hougang Central GLS site — is a 99-year leasehold integrated development in District 19, Singapore. It combines approximately 835 private homes, a new Integrated Transport Hub bringing Hougang MRT (NE14) and the town's bus interchange under one roof, and a mall of roughly 300,000 sq ft net lettable area owned in full by CapitaLand Integrated Commercial Trust. The lease runs 99 years from the site's award on 14 January 2026.
The site measures 46,898 sqm — about 504,860 sq ft, or 4.69 hectares — at a gross plot ratio of 2.5. HDB's Additional Conditions of Tender, published 29 May 2025, set permissible total gross floor area at 105,521–117,245 sqm with a residential minimum of 70,805 sqm, a bus interchange minimum of 6,500 sqm including a 400 sqm commercial concourse, and a commercial maximum of 39,940 sqm excluding that concourse. Those are confirmed figures from the primary tender document, not estimates.
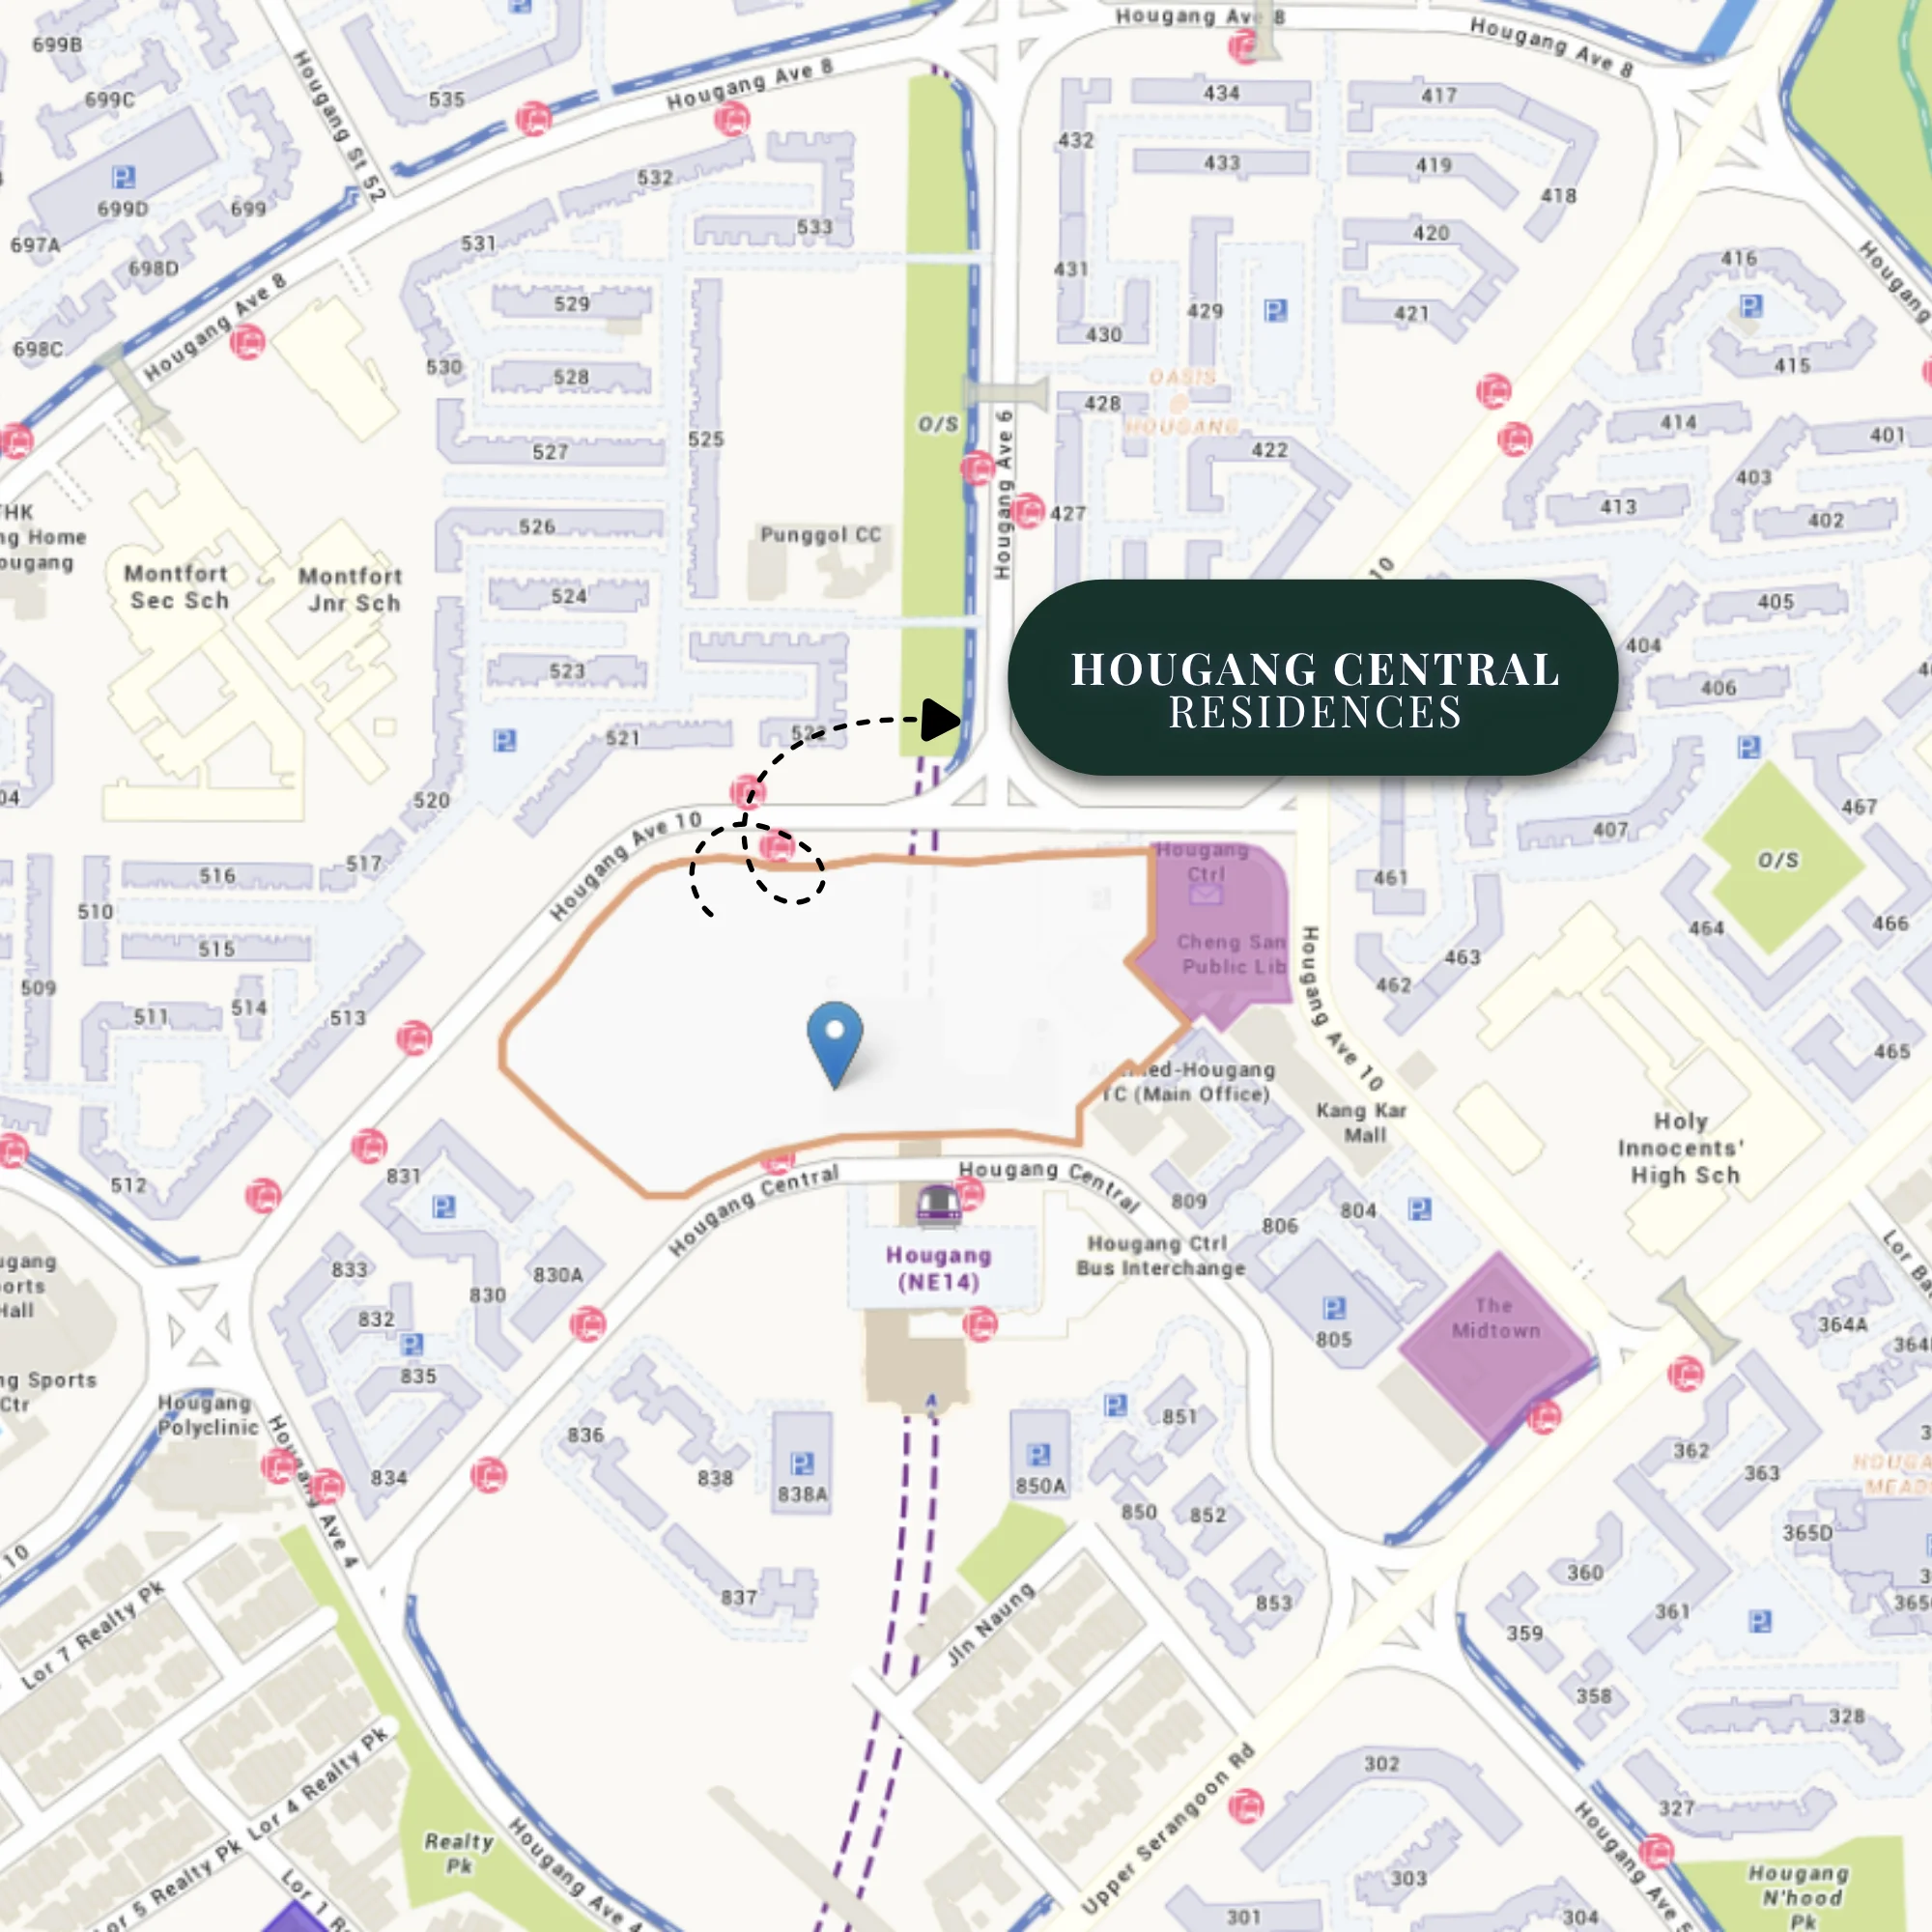
Today the site is the Hougang Central bus interchange, with Cheng San Public Library, Hougang Mall and Kang Kar Mall immediately across Hougang Central and the Ang Mo Kio–Hougang Town Council main office adjoining. The bus interchange is not being relocated away from the town centre — the tender requires it to be rebuilt inside the new development, which is what makes the "integrated" description literal rather than promotional.
For buyers searching for the Hougang Central GLS launch date, the honest answer is that none has been announced. Internal planning points to an estimated preview around Q2 2027, with estimated completion in 2031–2032. Both are estimates. What is confirmed is the land price, the site's dimensions, the consortium behind it, and the transport obligations written into the tender — and those are the facts that will shape the eventual price list.
Three things are happening on one plot of land at the same time, and each would be notable on its own. The bus interchange is being rebuilt inside the development rather than moved. Hougang MRT is being consolidated with it into a single Integrated Transport Hub, replacing today's underground walkway link. And Hougang MRT gains a second rail line when Cross Island Line Phase 1 opens, targeted by 2030 under LTA's committed and funded programme. The result is that the town's transport centre and its newest homes become the same address.
The retail piece is the part most easily underestimated. Hougang has historically been under-supplied on retail space relative to its population, and the new mall — at around 300,000 sq ft net lettable area — will be the largest in the town on completion. Crucially, CICT owns it outright rather than a developer selling strata units and exiting. A REIT holds a mall as a recurring income asset, which means the incentive to keep the tenant mix strong runs for decades, not just through a sales campaign.
There is a precedent worth looking at closely. The same CapitaLand Development and UOL pairing built Parktown Residence on the Tampines Avenue 11 site — also a bus-interchange-integrated mixed-use development — which launched in February 2025 and sold 1,041 of 1,193 units, or 87%, on its launch weekend. Hougang Central applies the same model to a station that is already operational, in a town centre that is already mature.
The counterweight, stated plainly: at $1,179 psf ppr this is the highest land rate ever paid for an OCR mixed-use GLS site — roughly 20% above Chencharu Close in Yishun ($980 psf ppr, September 2025) and about 33% above Tampines Avenue 11 ($885 psf ppr, July 2023). Connectivity of this kind is not free, and a buyer prioritising the widest margin of safety over the strongest transport package should look at the lower-land-cost alternatives first. Both things are true at once.
Hougang Central Residences is one of a very small number of Singapore developments physically integrated with an already-operational MRT station. Hougang MRT (NE14) on the North East Line sits within the development's own footprint, reached through the new Integrated Transport Hub rather than by walking to it. The distinction matters most on the days it rains, and it is the single clearest reason the site drew a record land rate.
Rail connections from Hougang MRT (NE14):
Cross Island Line Phase 1 timing is per LTA's published programme. Journey times will depend on the final station configuration and are not quoted here as measured figures.
For drivers, the Kallang–Paya Lebar Expressway connects the precinct toward the city centre, Changi and the East Coast, while the Central Expressway serves the CBD and the north. Tampines Road and Upper Paya Lebar Road are the arterial roads bounding the site, giving local access without depending on a single route out of the estate.
From a rental standpoint, an integrated transport hub creates its own tenant base: the mall's retail and food-and-beverage operators, transport operations staff, and the multi-year pool of project-linked renters that Cross Island Line construction and eventual operations bring into the immediate precinct. District 19's rental market is already active — The Florence Residences, the nearest large-scale comparable, has sustained consistent rental transaction volume, which is a fairer proxy for this location than any pre-launch projection.
A note on realism: no rental track record exists for Hougang Central Residences itself, because it has not been built. Any yield figure quoted for a pre-launch project is a modelled estimate built on a comparable's rents, and should be treated as such. What can be assessed today is the structural demand case — and on connectivity, it is the strongest in the district.
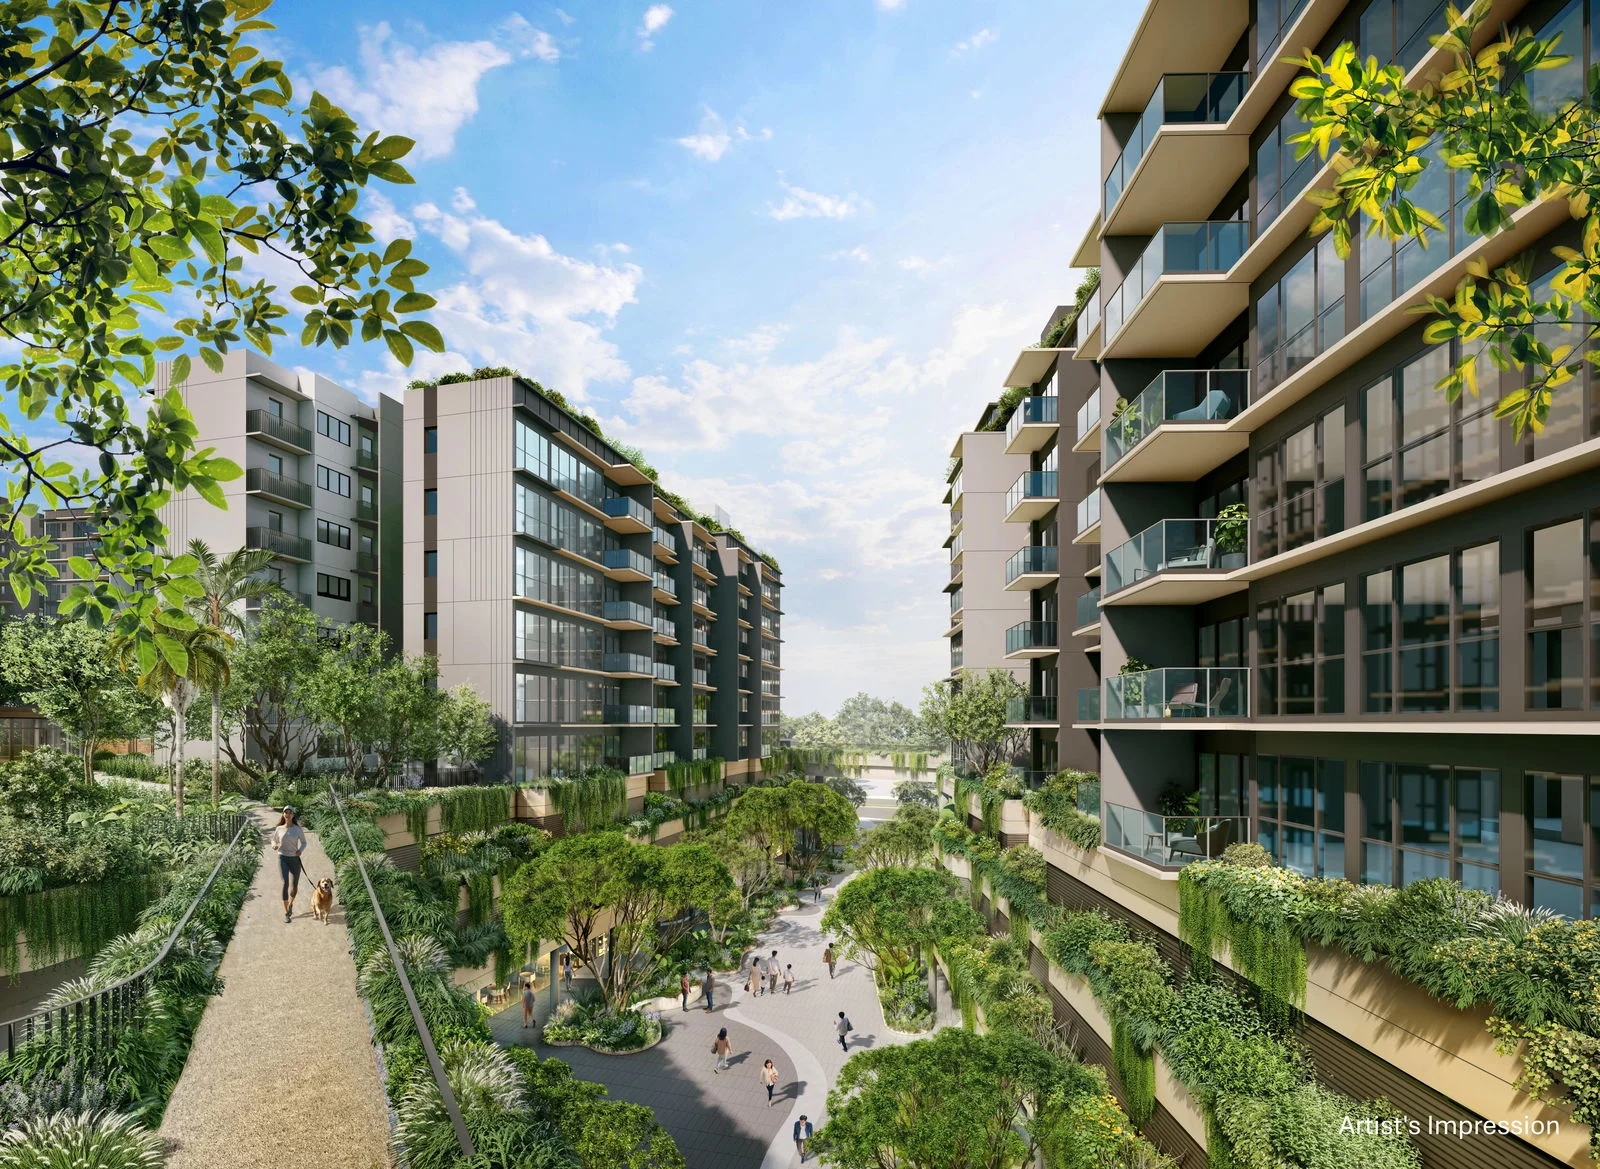
A 4.69-hectare parcel at gross plot ratio 2.5 — homes, landscape decks and facilities above the transport hub and mall. The official site plan is expected in late 2026 or early 2027.
Hougang Central Residences is built into the new Integrated Transport Hub at Hougang MRT (NE14). Residents reach the North East Line platform and the bus interchange without leaving the development — and from 2030, the Cross Island Line from the same station.
For drivers, the Kallang–Paya Lebar Expressway and the Central Expressway both serve the precinct, with Tampines Road and Upper Paya Lebar Road bounding the site.
Download the Hougang Central Residences e-brochure for the site facts, transport hub detail, retail plans and unit-type overview — plus the price list and floor plans the moment they are released.
Hougang Ave 10 / Hougang Central, OCR
MRT + Bus Interchange + Mall
From award, 14 January 2026
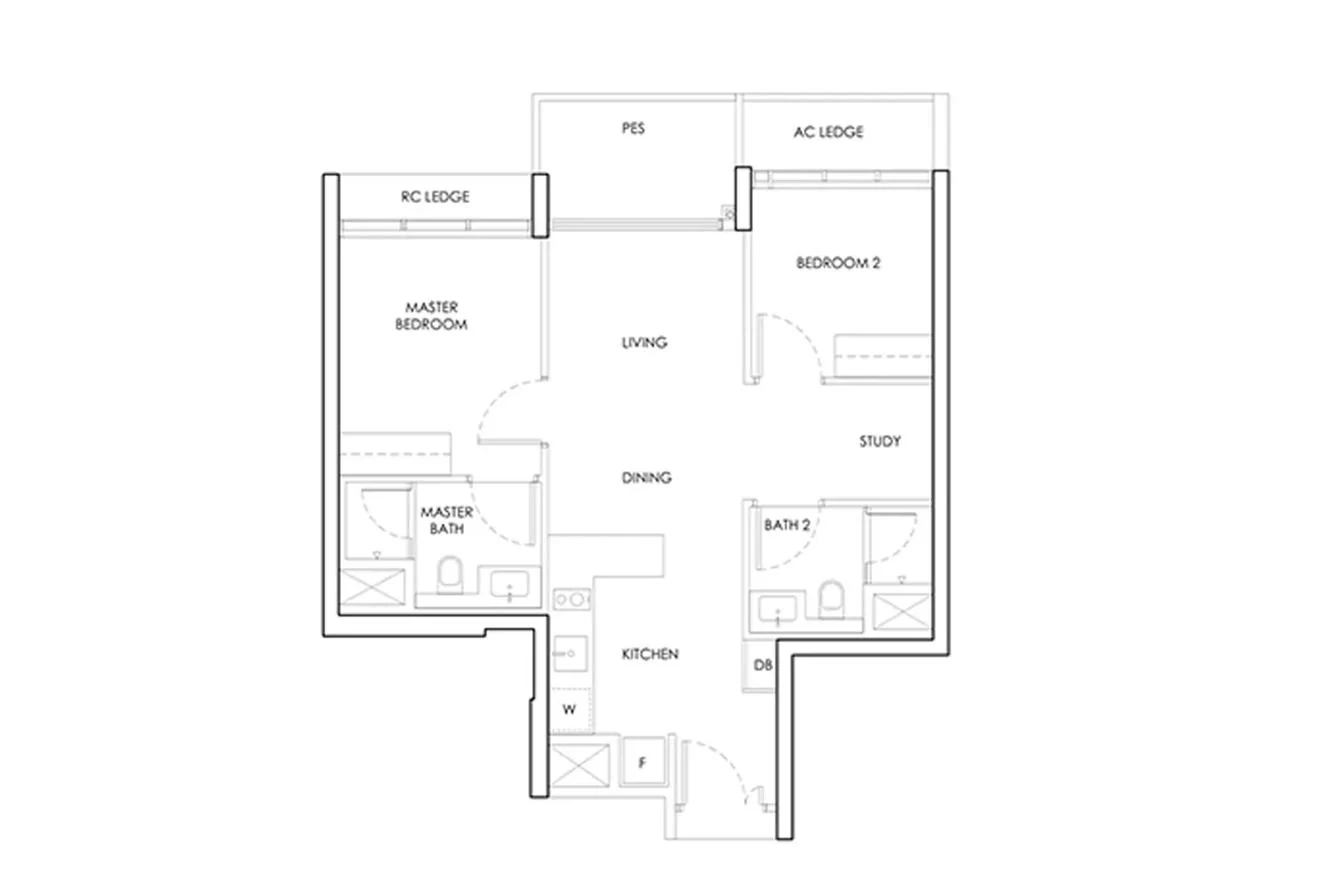
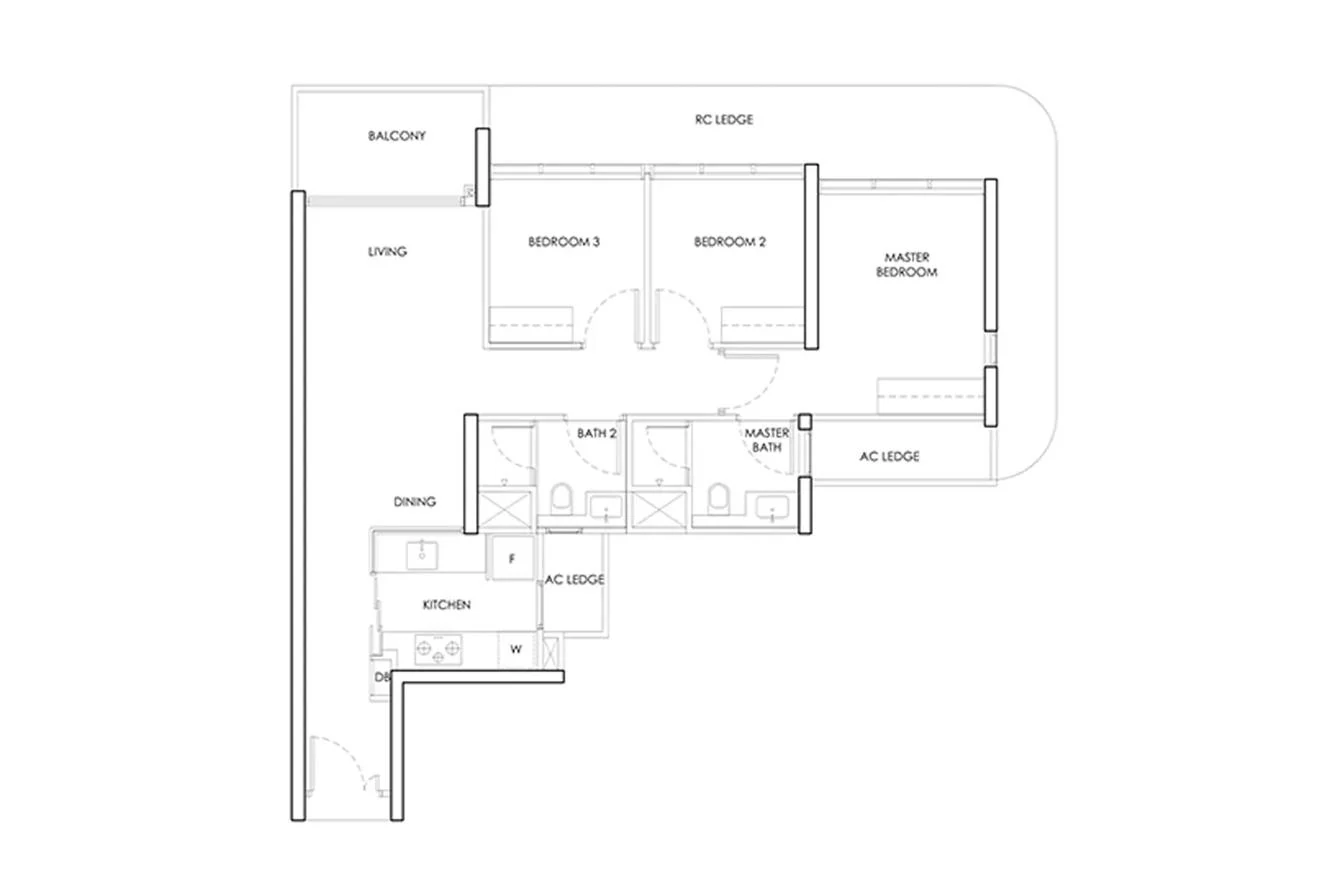
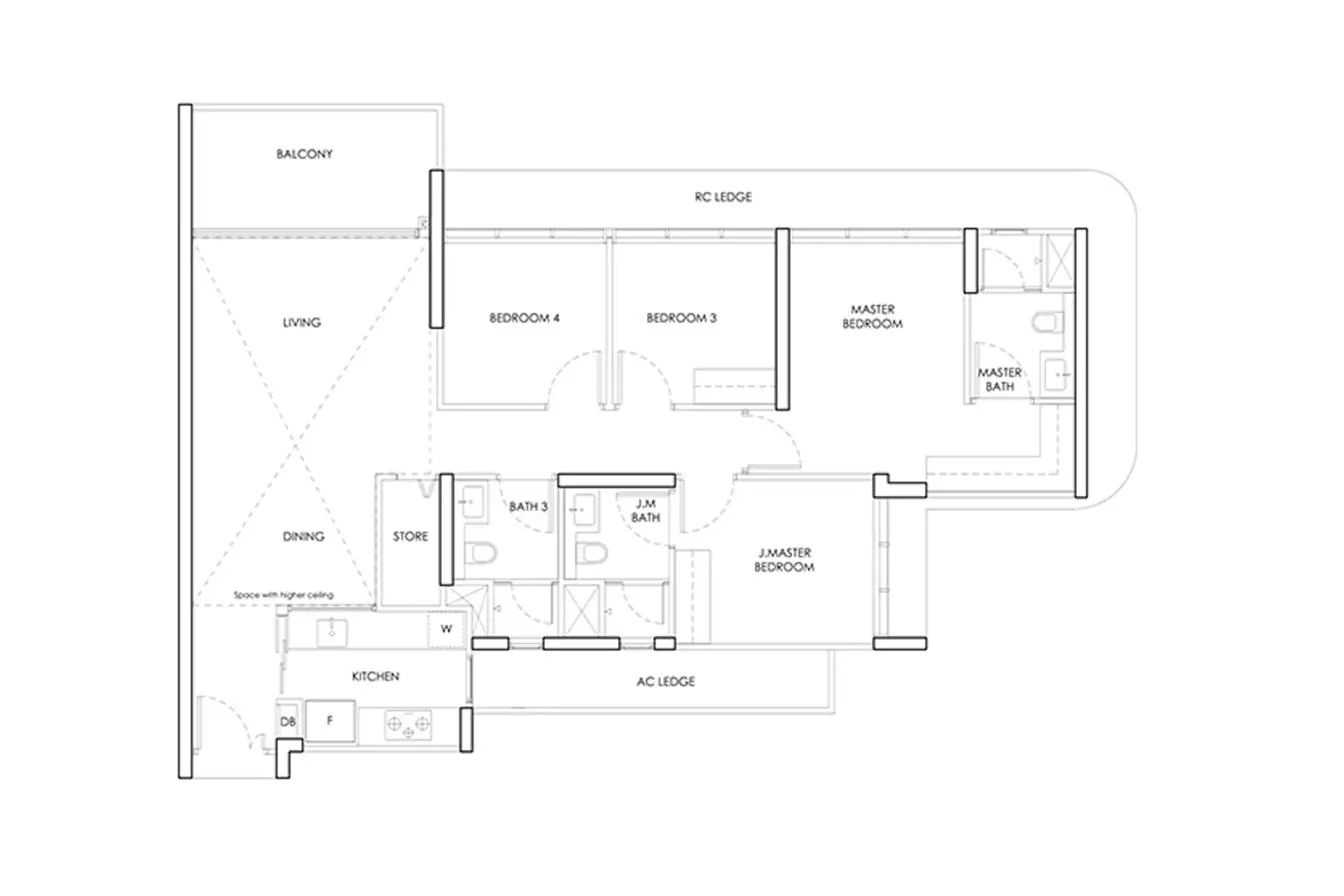
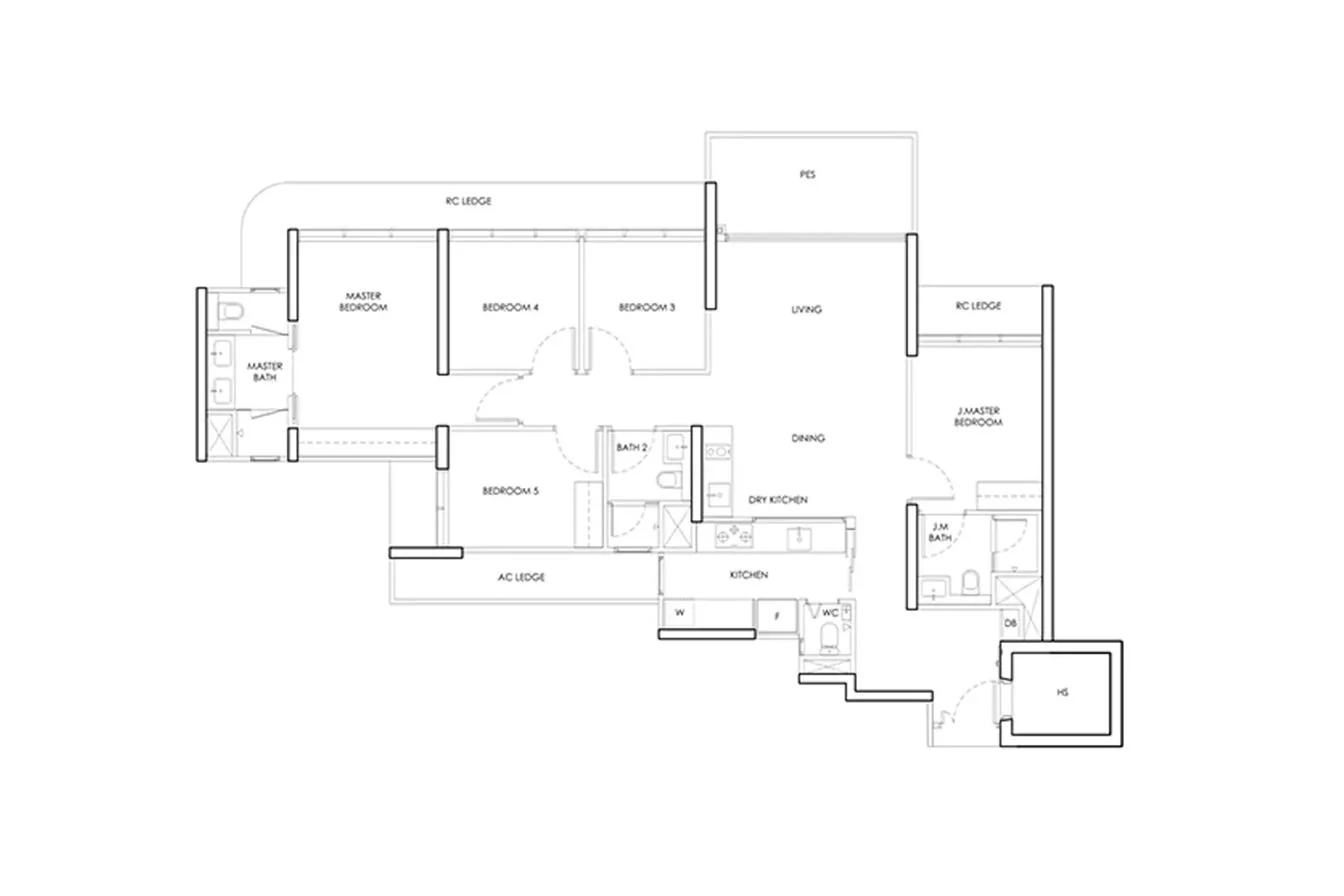
The developer has not released the official floor plans for Hougang Central Residences. The layouts below are indicative unit-type templates only — shown to illustrate typical configurations at each bedroom count, not the actual plans for this project, and not to be relied on for room dimensions, orientation or unit sizes. Register to receive the official plates the day they are published.
One-bedroom and one-bedroom-plus-study layouts are expected in the mix; plans for all types will be published by the developer at preview.
The development is built on the bus interchange footprint and integrates directly with Hougang MRT (NE14) — with a Cross Island Line interchange committed for 2030. No other Hougang address has ever offered this, and only a handful of Singapore launches in any district can claim genuine station integration. That is a permanent, structural differentiator rather than a marketing angle.
Hougang has had no new private launch since The Florence Residences in 2019. Meanwhile roughly 31,000 HDB flats of three rooms and larger across Hougang, Punggol, Sengkang and Serangoon reached the end of their Minimum Occupation Period between 2020 and 2026 (ERA Research). Local upgraders who wanted to stay in the neighbourhood have had nowhere new to buy.
CapitaLand Integrated Commercial Trust owns 100% of the commercial component — around 300,000 sq ft of retail, the largest mall in Hougang on completion. A REIT holds a mall as a recurring income asset, giving it a financial incentive to keep the tenant mix strong for the life of a resident's hold, rather than through a sales campaign. That alignment is uncommon among mixed-use GLS awards.
At $1,179 psf ppr this is the highest land rate ever paid for an OCR mixed-use GLS site — about 20% above Chencharu Close ($980 psf ppr, September 2025). Analyst commentary projects a launch range of roughly $2,500–$2,600 psf (estimated), materially above The Florence Residences' current resale of about $1,870–$1,900 psf. The connectivity premium is real; so is the compressed margin of safety. A buyer optimising purely for entry price should compare the lower-land-cost alternatives before deciding.
The Hougang Central Residences sales gallery has not opened — an estimated preview is expected around Q2 2027. Register now to be notified the moment appointments open.
Hougang MRT (NE14) and the rebuilt bus interchange sit inside the development's own Integrated Transport Hub. There is no walk to the station, no exposed last hundred metres, and no separate journey to catch a bus. From 2030 the Cross Island Line adds a second axis from the same platform level — turning a single-line town centre into a two-line interchange while residents are still waiting on their keys.
Up to 39,940 sqm of commercial floor area is permitted under the tender — around 300,000 sq ft of net lettable retail owned outright by CapitaLand Integrated Commercial Trust. Groceries, dining, everyday services and a town plaza sit beneath the homes rather than a bus ride away. Because CICT holds the mall as a long-term income asset, the quality of that tenant mix is its own commercial priority for decades.
Hougang is not a precinct waiting to be built. Cheng San Public Library, Hougang Polyclinic, Hougang Sports Centre, community clubs, wet markets, coffee shops and an established school belt are already in place around the site. A buyer here inherits a functioning neighbourhood on day one and receives the new transport hub and mall on top of it — the reverse of the usual new-town trade-off, where amenity arrives years after the keys.
There is no official Hougang Central Residences price list yet, and there will not be one until the developer completes planning approvals and opens the preview. What is confirmed is the land cost: S$1,500,738,338, or $1,179 psf per plot ratio, awarded 14 January 2026. That number anchors everything that follows.
Analyst commentary published after the award projects an indicative launch range of $2,500–$2,600 psf (estimated) — Huttons' Mohan Sandrasegeran via EdgeProp, January 2026. Working from the land rate: add roughly $420 psf of construction cost for a build carrying a transport hub and mall, plus roughly $150 psf of financing, fees and margin buffer, and the implied developer breakeven lands near $1,750 psf. Against a $2,500–$2,600 launch range, that implies a margin broadly in line with typical Singapore GLS project economics. Every figure in that derivation except the land rate is an estimate — it is shown so the reasoning is checkable, not because it is confirmed.
| Hougang Benchmark | Type | Price (psf) |
|---|---|---|
| Hougang Central Residences (this site) | New launch, est. Q2 2027 | $2,500–$2,600 (est.) |
| The Florence Residences (2019) | Resale | ~$1,870–$1,900 |
| Midtown Residences (2016) | Resale, 12-mth avg | ~$1,595 |
Buyers comparing Hougang Central Residences vs The Florence Residences are really comparing two different products. The Florence Residences is a 1,410-unit standalone condominium off Hougang Avenue 2, completed after a March 2019 launch at around $1,450 psf and now reselling at roughly $1,870–$1,900 psf — about a 15 to 18 minute walk from Kovan MRT (NE13). It is the established, family-oriented mega-development in the district, and it has demonstrated genuine resale liquidity at scale.
Hougang Central Residences is smaller at approximately 835 units, newer, and integrated directly with Hougang MRT and a 300,000 sq ft mall. It will launch at a materially higher psf. The trade is straightforward: Florence offers a proven track record and a lower entry price; Hougang Central offers connectivity and retail no existing Hougang project can match, at the town's highest-ever entry point.
The most useful cross-shop is Chencharu Close in Yishun, awarded September 2025 at $980 psf ppr with a bus interchange and hawker centre — also integrated, also OCR, and materially cheaper on land cost. If a wider margin of safety matters more than the strongest transport package, Chencharu Close deserves a serious look first, accepting a walk to Khatib MRT (NS14) rather than in-building access and no REIT-anchored mall. Stated plainly because a buyer is better served by the comparison than by a one-sided pitch.
The arithmetic deserves honesty. Median Hougang resale prices over January–November 2025 were around $675,000 for a 4-room flat and $830,000 for a 5-room (EdgeProp/Realion). After a typical CPF refund with accrued interest and an outstanding loan balance, a median 5-room seller may be left with net cash and CPF proceeds in the region of $400,000 — illustrative only, since these vary materially by household.
At an estimated launch of $2,500–$2,600 psf, a two-bedroom unit is the realistic reach for that profile, with a three-bedroom typically requiring additional savings, a larger or newer flat, or dual income. That is not a reason to walk away; it is a reason to run the actual numbers early, before a preview weekend forces the question.
The Hougang Central Residences developer consortium is CapitaLand Development, UOL Group, Singapore Land Group and Kheng Leong on the residential side, with CapitaLand Integrated Commercial Trust holding 100% of the commercial component. The Hougang Central Residences launch date has not been announced; an estimated preview around Q2 2027 and estimated completion in 2031–2032 are planning projections rather than developer statements. The next real milestone is the site plan and unit mix, expected in late 2026 or early 2027 — that is when stack selection, facing and layout efficiency become answerable questions instead of guesses.
The questions buyers ask most about the Hougang Central GLS site, answered with sourced figures and clearly-labelled estimates.
Last updated:
Be first to receive the site plan, unit mix, official floor plans and price list for the Hougang Central GLS integrated development.